Abbott India Rank: Market Position & Key Competitors
Abbott India Market Position Explorer
Click on a company below to see how it compares to Abbott India. Understand why lower revenue rank doesn't mean lower profitability.
Abbott India
Rank: #8-12Focus: Branded Rx & Devices
Sun Pharma
Rank: #1Focus: Generics & Specialty
Cipla
Rank: #2-3Focus: Respiratory & Generics
Quick Comparison Table
| Company | Primary Focus | Est. Revenue Rank | Key Strength |
|---|---|---|---|
| Abbott India | Branded Rx & Devices | #8-12 | High margins & diagnostic tech |
| Sun Pharma | Generics & Specialty | #1 | Global scale & US exports |
| Cipla | Respiratory & Generics | #2-3 | Affordable access & brand recall |
| Lupin | Generics & Cardiac | #6-7 | US market penetration |
You are probably wondering where Abbott India actually stands in the crowded landscape of Indian healthcare. It is a fair question. The Indian pharmaceutical sector is massive, fragmented, and fiercely competitive. You have giants like Sun Pharma and Cipla dominating headlines, while multinational corporations (MNCs) hold steady niches. So, what is the real story with Abbott?
Here is the short answer: Abbott India consistently ranks within the top 10 to top 15 pharmaceutical companies in India by revenue and market capitalization. However, this number shifts depending on whether you look at total sales, net profit, or specific therapeutic segments. Unlike domestic players that rely heavily on generic drugs, Abbott focuses on branded formulations and specialized medical devices. This strategy gives them higher margins but limits their volume compared to mass-market generics makers.
Understanding the Ranking Metrics
Ranks are not static numbers. They depend entirely on what you measure. If you look at pure revenue, Abbott India often sits around the 8th to 12th position among listed pharma companies. But if you look at profitability per rupee of sales, they frequently outperform larger domestic peers. Why? Because selling a branded heart medication yields better returns than selling thousands of strips of generic paracetamol.
When analysts talk about "rank," they usually refer to one of three things:
- Revenue Rank: Total money coming in from sales across all products.
- Market Cap Rank: The total value of the company's shares on the stock exchange.
- Segment Rank: Where they stand in specific areas like cardiology, diabetes, or diagnostics.
For most investors and industry watchers, revenue and market cap are the primary indicators. As of late 2026, Abbott India maintains a strong presence in the Nifty Pharma index. Their stability appeals to conservative investors who prefer consistent dividends over high-risk growth bets common in smaller generic firms.
How Abbott India Compares to Domestic Giants
To understand the rank, you must compare Abbott to its neighbors. Let’s look at the big names. Sun Pharmaceutical Industries Ltd holds the #1 spot for years due to its massive export business and diverse portfolio. Cipla follows closely, known for respiratory care and affordable generics. Dr. Reddy’s Laboratories also competes strongly in the US markets.
Where does Abbott fit? They do not compete directly with Sun Pharma on price-sensitive generics. Instead, Abbott targets premium segments. Think of it this way: if Sun Pharma is the Walmart of Indian pharma-high volume, low margin-Abbott is more like a specialized boutique retailer. They sell fewer units, but each unit brings in significantly more profit.
| Company | Primary Focus | Estimated Revenue Rank (India) | Key Strength |
|---|---|---|---|
| Sun Pharma | Generics & Specialty | #1 | Global scale & US exports |
| Cipla | Respiratory & Generics | #2-3 | Affordable access & brand recall |
| Dr. Reddy’s | Generic Formulations | #4-5 | Innovative generics |
| Abbott India | Branded Rx & Devices | #8-12 | High margins & diagnostic tech |
| Lupin | Generics & Cardiac | #6-7 | US market penetration |
This table highlights a crucial distinction. Abbott’s lower revenue rank does not mean weakness. It reflects a different business model. While Lupin might ship millions of boxes of blood pressure meds, Abbott sells advanced cardiac stents and glucose monitors alongside their branded pills. These devices command higher prices and foster deeper doctor relationships.
The Diagnostic Advantage
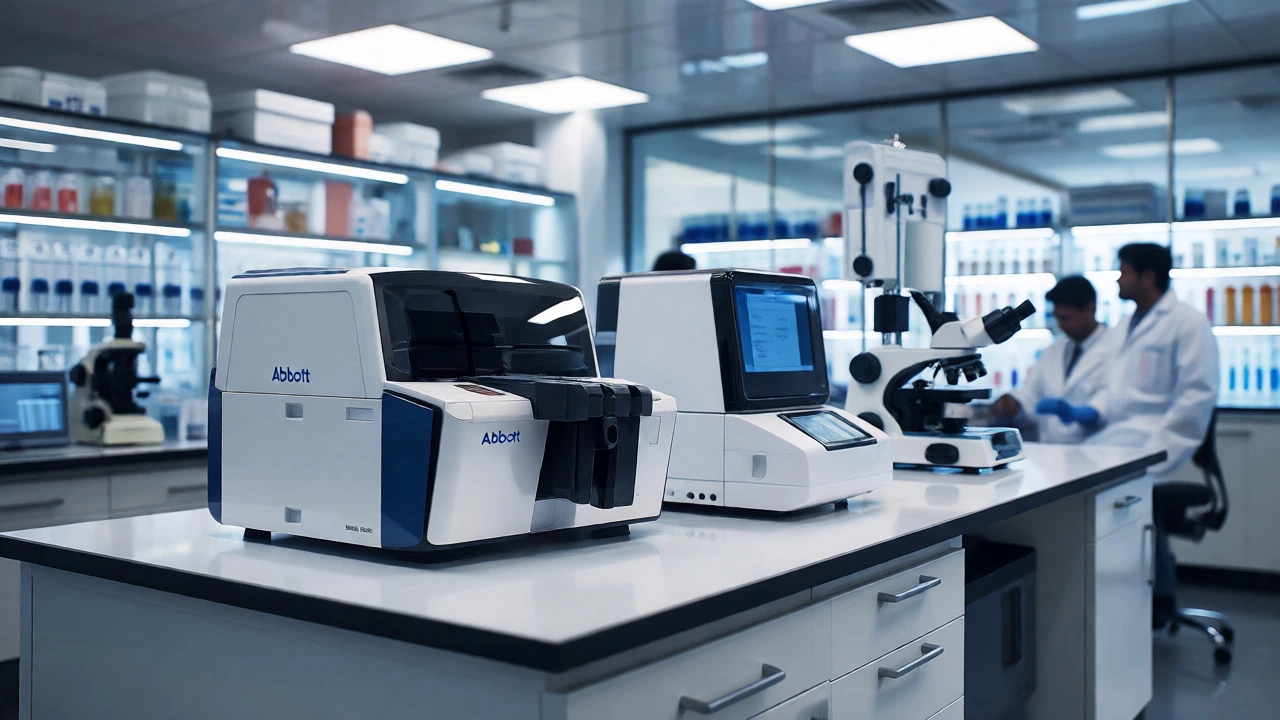
One reason Abbott India holds such a resilient position is their dominance in diagnostics. Most people think of Abbott only as a pill maker. That is a mistake. Their diagnostic division generates substantial revenue through laboratory equipment and point-of-care testing kits. In hospitals across Mumbai, Delhi, and Bangalore, you will find Abbott analyzers running blood tests every hour.
This segment acts as a moat. Once a hospital installs an Abbott analyzer, they tend to stick with Abbott reagents and consumables for years. This recurring revenue stream stabilizes their financials even when drug sales fluctuate. Domestic competitors struggle here because manufacturing complex diagnostic machinery requires significant R&D investment and technical support networks. Abbott has had decades to build this infrastructure globally.
Consider the impact during recent health crises. When demand for rapid antigen tests surged, Abbott was already positioned with existing supply chains. Companies that tried to enter the diagnostics space late faced logistical nightmares. Abbott’s early entry gave them a head start that translates directly into market share retention today.
Therapeutic Areas Driving Growth
What exactly is Abbott selling to maintain its rank? Three main pillars support their growth:
- Cardiovascular Health: From statins to anti-hypertensives, Abbott has a deep portfolio here. Doctors trust these brands for chronic disease management.
- Diabetes Care: Insulin pens and glucose meters form a critical part of their sales. With India’s diabetic population rising, this segment continues to expand.
- Gastroenterology: Probiotics and gut-health supplements have seen explosive growth. Abbott leverages global research to launch locally relevant products quickly.
Notice how these areas align with modern lifestyle diseases. India faces a dual burden of infectious and non-communicable diseases. Abbott targets the latter effectively. By focusing on chronic conditions that require lifelong treatment, they ensure customer retention. A patient diagnosed with hypertension today will likely buy Abbott medications for the next twenty years.
Challenges Facing the Brand
No ranking comes without risks. Abbott India faces specific challenges that could affect future positions. First, regulatory scrutiny in India has tightened. The National Pharmaceutical Pricing Authority (NPPA) frequently revises price caps on essential medicines. Since Abbott relies on branded drugs, any forced price cut hits their margins harder than it affects low-cost generics.
Second, competition from Indian MNC clones is rising. Local companies now produce high-quality equivalents at slightly lower prices. Doctors are becoming more cost-conscious, especially in tier-2 and tier-3 cities. Abbott must constantly innovate to justify its premium pricing.
Third, supply chain disruptions remain a concern. While Abbott sources many raw materials domestically, some specialized components still come from abroad. Global logistics hiccups can delay product availability, allowing competitors to capture temporary market share.
Why Investors Watch Abbott’s Rank
If you are an investor, why should you care about the exact rank number? Because it signals stability. Abbott India is considered a defensive stock. During economic downturns, people still need medicine. They might skip buying new clothes, but they won’t stop treating their diabetes. This inelastic demand protects Abbott’s revenue streams.
Furthermore, Abbott pays healthy dividends. For long-term holders, this cash flow matters more than aggressive growth metrics. Compare this to smaller pharma startups that reinvest everything into R&D. Those companies might grow faster, but they carry higher risk. Abbott offers a balanced profile: moderate growth, steady income, and low volatility.
Analysts often upgrade or downgrade stocks based on quarterly earnings reports. If Abbott beats expectations despite inflationary pressures, their rank in institutional portfolios improves. Conversely, if a competitor launches a superior device, Abbott might lose ground in specific segments, prompting investors to reassess its valuation.
Future Outlook for Abbott India
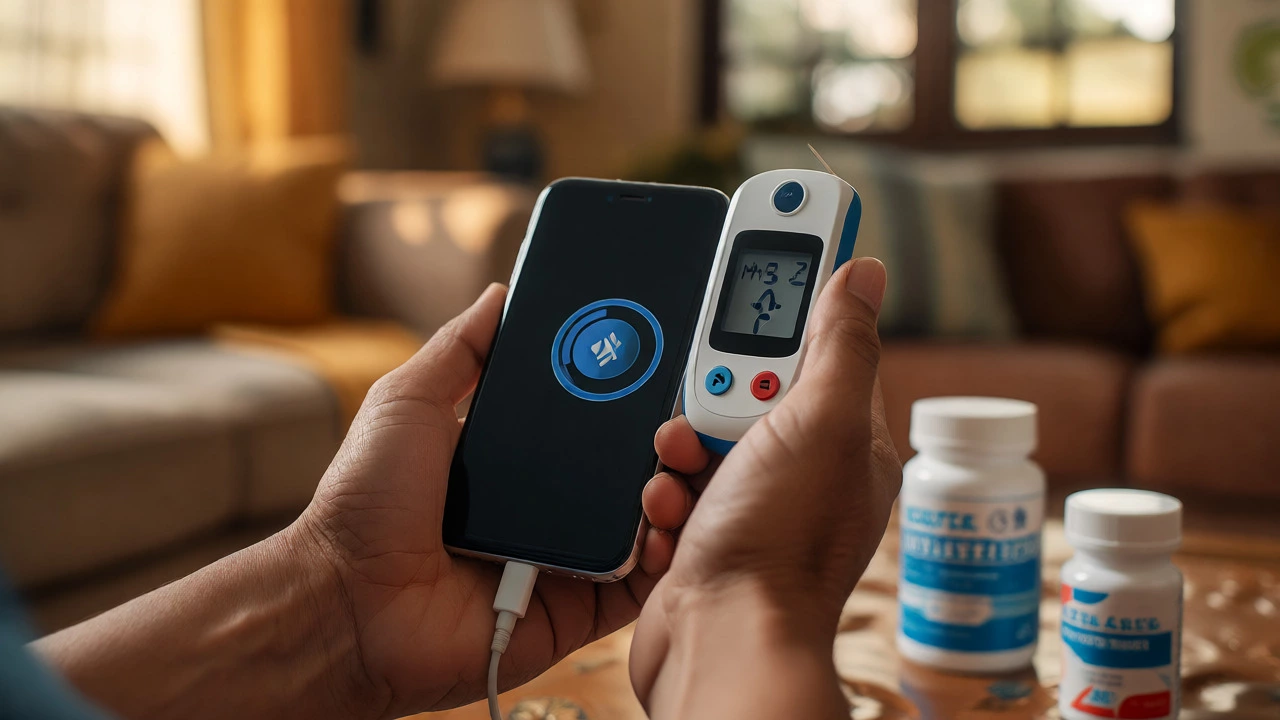
Looking ahead to 2027 and beyond, several trends will shape Abbott’s standing. Digital health integration is key. Abbott is investing in connected devices that sync data to mobile apps. Imagine a glucose meter that automatically alerts your doctor if levels spike. This technology adds value beyond the physical product, strengthening brand loyalty.
Telemedicine adoption also benefits Abbott. As online consultations become normal, prescriptions for branded chronic meds increase. Patients receive digital scripts and order refills via e-pharmacies. Abbott’s strong distribution network ensures these orders reach remote areas efficiently.
Finally, sustainability initiatives play a role. Modern consumers and regulators demand eco-friendly practices. Abbott’s efforts to reduce plastic waste in packaging and improve energy efficiency in factories resonate well. These intangible factors influence corporate reputation, which indirectly supports market positioning.
In essence, Abbott India’s rank is not just a number. It reflects a strategic choice to prioritize quality, innovation, and reliability over sheer volume. While they may never beat Sun Pharma in total sales, they dominate in profitability and brand equity. Understanding this nuance helps you appreciate their true place in the industry hierarchy.
Is Abbott India a government-owned company?
No, Abbott India is a private limited subsidiary of Abbott Laboratories, a US-based multinational corporation. It operates independently in the Indian market but adheres to local regulations set by bodies like the CDSCO and NPPA.
Which is bigger, Cipla or Abbott India?
Cipla is generally larger in terms of total revenue and global footprint. Cipla focuses heavily on generics and respiratory care with massive volume sales. Abbott India generates less total revenue but often achieves higher profit margins due to its focus on branded specialty drugs and medical devices.
What is Abbott India’s best-selling product category?
Cardiovascular medications and diagnostic solutions are among their strongest performers. Additionally, their gastroenterology products, including probiotics, have seen significant growth in recent years due to increased awareness of gut health.
Does Abbott India manufacture vaccines?
While Abbott Laboratories globally engages in vaccine development, Abbott India primarily focuses on established pharmaceutical products and medical devices rather than being a primary vaccine manufacturer for the domestic Indian market.
How does Abbott India maintain its high margins?
They maintain high margins by avoiding the commoditized generic market. Instead, they sell branded drugs and proprietary medical devices where doctors and patients are willing to pay a premium for perceived quality, reliability, and after-sales service.